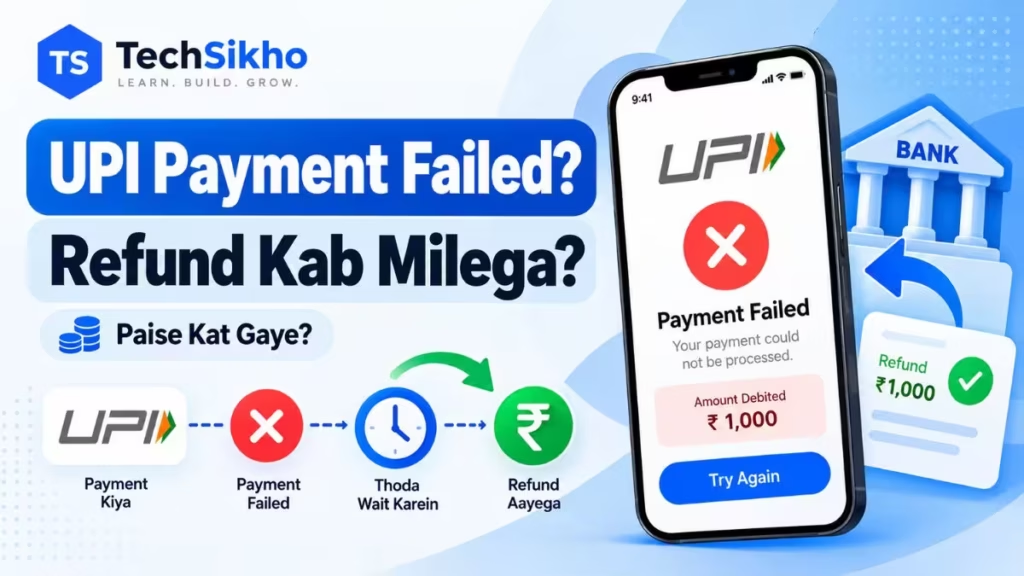
UPI Payment Failed Lekin Paise Kat Gaye? Dukandar dobara payment maang raha ho to pareshani aur badh jaati hai. Pehle app ka status aur bank statement check karein. Sirf debit ka SMS payment complete hone ya fail hone ka proof nahi hai.
UPI refund kab milega, yeh actual transaction par depend karta hai. Personal transfer aur merchant payment ke applicable failed cases ki deadlines alag hain. Neeche zaroori checks, timeline aur complaint process samjhein.
Jankari ki jaanch: 14 October 2026. Yeh general educational guide hai; final transaction status bank records se confirm hoga.
UPI Payment Failed Lekin Paise Kat Gaye To Sabse Pehle Kya Kare?
- Transaction kholein: UPI app ki History me wahi payment chunein. Failed, Pending/Processing ya Successful status aur debit hue bank account ko dekhein.
- Bank statement check karein: Mobile banking, net banking ya passbook me amount aur date milayein. Refund ki credit/reversal entry bhi dekhein; SMS na aane par bhi credit ho sakta hai.
- Receiver se confirm karein: Unse sambandhit bank account ka statement check karne ko kahein. Sirf notification ya dukaan ke soundbox ki awaaz par depend na karein.
- Proof save karein: Amount, date-time, receiver/merchant details, transaction reference aur status ka screenshot rakhein. Complaint ticket mile to use bhi sambhalein.
- Dobara payment se pehle verify karein: Pending payment baad me complete ho sakta hai. Zaroori alternate payment karna pade to merchant se pehle baat karein aur dono receipts rakhein.
Refund usi account me dekhein jisse paise kate the. Google Pay ya PhonePe me kai accounts linked hon to doosre account ka balance dekhne se confusion ho sakta hai. Google Pay ki bank statement guide me bhi transaction reference aur amount milane ka tarika diya hai.
UPI Payment Failed Hone Ke Common Reasons
Bank server ki dikkat, network interruption, transaction timeout, beneficiary bank me processing delay ya temporary technical issue ki wajah se payment atak sakta hai. Beneficiary ka matlab paise receive karne wala vyakti hai. Kabhi debit ho jata hai, lekin agle system se confirmation samay par nahi milta.
Yeh possible reasons hain, confirmed diagnosis nahi. NPCI ki UPI ecosystem glossary me Technical Decline (TD) ke under bank ya NPCI ke system aur network issues ka zikr hai. Exact reason bank se poochhein.
UPI Refund Kitne Din Me Aata Hai?
RBI ki failed transaction guidelines ke UPI rules me neeche diye do scenarios alag hain. Framework customer ki galti ke bina fail hue applicable domestic transactions ke liye hai, jahan sender aur receiver India me hain.
| Transaction ki sthiti | Auto-reversal deadline | Deadline ke baad delay |
|---|---|---|
| Personal transfer: account debit, receiver ko credit nahi | Credit nahi ho sake to T+1 tak | Rs 100 per day ka framework |
| Merchant payment: account debit, merchant ko transaction confirmation nahi | T+5 tak | Rs 100 per day ka framework |
T transaction ki calendar date hai. T+1 agla calendar din aur T+5 us date se paanch calendar din baad hai. Inhe working days ya payment ke exact samay se 24/120 ghante na samjhein. Yeh maximum prescribed deadlines hain; reversal pehle bhi ho sakta hai.
Dukaan par QR scan karna akela merchant classification ka proof nahi; QR personal account ka bhi ho sakta hai. Doubt ho to bank se transaction type confirm karein. Successful purchase ke baad order cancel hone ka merchant refund, upar wale failed-payment reversal se alag hai.
App me dikh raha estimated support time RBI ki applicable deadline ko replace nahi karta. NPCI UPI FAQs failed debit ka refund ek ghante me na mile to bank support se contact karne ko kehte hain. Yeh contact karne ki salah hai, universal one-hour refund guarantee nahi.
Pending, Failed Aur Successful Payment Me Kya Difference Hai?
- Failed: Payment complete nahi hua. Debit hua hai to reversal entry dekhein aur applicable deadline ke hisab se follow-up karein.
- Pending/Processing: Final confirmation abhi nahi mili. Baad me Success ya Failed ho sakta hai; bina verify kiye dobara payment karna duplicate debit kara sakta hai.
- Successful, lekin receiver mana kar raha hai: Sahi receiver aur linked account verify karayein. Bank ko reference dekar payment trace karayein; ise automatic refund wala case na maan lein.
- Galat UPI ID par successful payment: Yeh normal technical failure nahi. App/bank ko batayein aur receiver se refund maangein. T+1/T+5 me automatic paisa wapas aane ki guarantee nahi.
Status ka basic farq NPCI UPI HELP guide me diya hai. Galat receiver wale case ke liye Google Pay ki incorrect transfer guidance bhi recipient aur bank se sampark karne ko kehti hai.
Google Pay, PhonePe, Paytm Ya BHIM Me Complaint Kaise Kare?
General workflow hai: Transaction History > Relevant Transaction > Help/Support/Report Issue > Complaint > Track Status. App version aur transaction status ke hisab se screen labels aur dispute option ki availability badal sakti hai.
- Google Pay: See transaction history me payment kholein, phir Having issues? aur relevant problem chunein. Official dispute guide kuch disputes ka option do din baad enable hone ki baat karti hai.
- PhonePe: Official grievance policy ke mutabik History me payment chunein aur Contact PhonePe Support kholein.
- Paytm: Payment ki details/reference save karke app ke Help & Support se issue raise karein.
- BHIM: Transactions me declined payment kholkar Report Issue use karein; yeh route NPCI ki BHIM information me diya hai.
Actual problem chunein aur ticket number save karein. Dispute button unavailable ho to bank complaint ke liye uske enable hone ka wait zaroori nahi.
Bank Me UPI Complaint Kaise Register Kare?
Jis account se debit hua, us bank ki official app, website, verified helpline ya branch se contact karein. UPI failed transaction complaint likhit form/email ya complaint portal se dene par follow-up ka record milta hai. Helpline par complaint ki hai to acknowledgement maangein.
- Amount, transaction ki date-time aur debit hue account ki pehchan.
- Receiver ka naam/UPI ID, merchant details aur transaction reference.
- App status ka screenshot aur relevant bank statement.
- App support ticket aur pehle mile replies, agar available hon.
Complaint me likhein: “UPI payment debit hua, receiver ko credit nahi mila aur reversal bhi nahi aaya. Kripya transaction trace karke status, reversal deadline aur applicable compensation batayein.” Apni actual problem ke hisab se wording badlein.
Complaint number, receive hone ki date aur expected response date note karein. Bank kahe refund ho gaya hai, to reversal date/reference maangkar statement se milayein. Documents verified support ko dein; social media par account details na daalein.
UPI Transaction ID, UTR Aur RRN Kahan Milega?
Transaction details kholkar reference number copy karein. Bank statement ki transaction narration me bhi reference mil sakta hai. Paytm ki RRN guide ke mutabik RRN ka full form Retrieval Reference Number hai; UPI ka yeh reference 12 digits ka hota hai aur Paytm ise UPI Ref No dikhata hai.
UTR ka matlab Unique Transaction Reference hai. Labels alag ho sakte hain: PhonePe ki help UPI payment ka 12-digit reference UTR kehti hai. Transaction ID app ka alag ID bhi ho sakta hai. Har ID ko RRN samajhkar na bharein.
NPCI form me 12-digit RRN maanga ho to wahi banking reference dein, merchant Order ID nahi. Number na mile ya do IDs ko lekar confusion ho to bank se RRN confirm karayein. Dono IDs save rakhein.
UPI Refund Nahi Mila To Complaint Aage Kaise Badhayein?
1. App Support Se Bank Grievance Tak
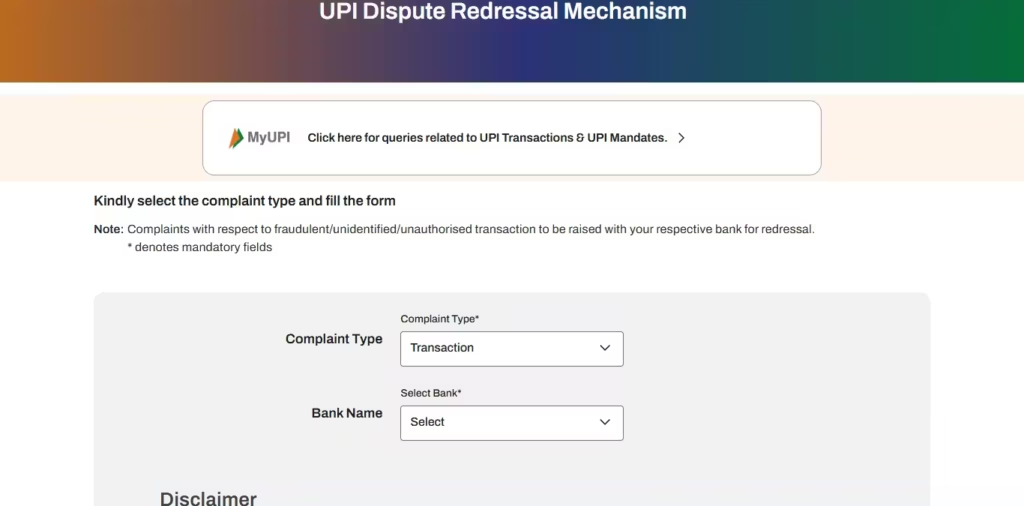
Existing app ticket par follow-up karein. Third-party app ke unresolved UPI issue ka escalation app se uske PSP bank, phir aapke account wale bank aur NPCI tak hota hai. PSP bank app ko UPI service dene wala partner bank hai; yeh aapke account wale bank se alag ho sakta hai. UPI dispute redressal mechanism me yeh order diya hai.
Bank support se hal na mile to uski official grievance policy ke mutabik grievance/nodal officer ko acknowledgement aur replies ke saath escalate karein. Bank complaint ka alag proof rakhein; sirf app chat ka record har case me kaafi nahi hoga.
2. NPCI Complaint Route
NPCI Complaint Portal par applicable UPI transaction complaint submit karein. Current form ke mutabik bank, date, amount aur reference details dein. NPCI complaint ko relevant member bank/institution tak pahunchata hai; resolution ki zimmedari us member ki hoti hai. CRN, yani Complaint Reference Number, save karke status track karein. Resolution ke liye bank se follow-up rakhein.
3. RBI Ombudsman: October 2026 Me Kaunse Rules Hain?
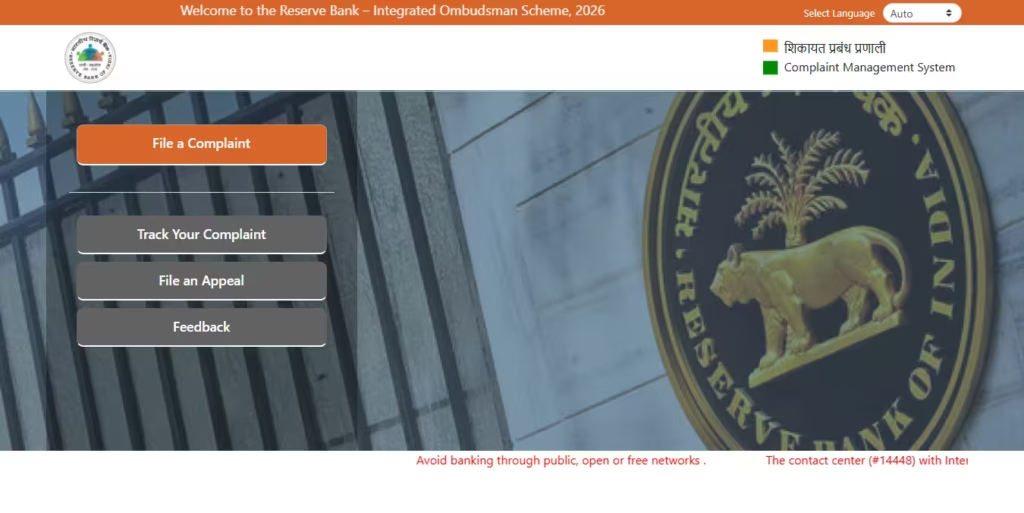
RBI ke 2026 Ombudsman FAQs ke mutabik Reserve Bank – Integrated Ombudsman Scheme, 2026 1 July 2026 se lagu hai aur 2021 scheme ko replace karti hai. Usse pehle received complaints aur unse jude appeals/awards par purane rules jaari hain. 2026 scheme ke Clause 10 ke zaroori points:
- Pehle concerned regulated entity ko complaint dein: UPI bank-account issue me sambandhit bank ke khilaf complaint aur uska proof zaroori hai.
- Reply nahi aaya: Entity ko complaint milne se 30 din, ya applicable RBI/NPCI/Card Network guideline ka samay, dono me jo zyada ho, beetne par escalation karein.
- Reply/resolution se santusht nahi: Reply mil chuka ho aur aap asantusht hon to upar wala waiting period poora hone ka intezar zaroori nahi.
- Filing limit: Applicable waiting period khatam hone ki date ya entity ki last communication ki date, dono me jo baad ki ho, usse 90 din ke andar Ombudsman complaint karein.
Refund ki T+1/T+5 deadline aur Ombudsman ka waiting period alag hain. Bank ko refund ke liye 30 din ki extra chhoot nahi milti. Bank ko initial complaint bhi applicable legal limitation ke andar deni hoti hai; deri na karein.
RBI CMS Portal par eligible complaint ke saath bank acknowledgement, reply, statement aur transaction proof lagayein. Service free hai. Complaint number save karein aur portal par status track karein. Filing se pehle scheme ki doosri eligibility conditions bhi check karein.
Rs 100 Per Day Compensation Kab Mil Sakta Hai?
Refund aapke kate hue paise ki wapsi hai. Compensation applicable deadline cross hone par delay ke liye alag payment hai. RBI framework me eligible compensation bina customer ke claim ka wait kiye, apne aap account me credit karna hota hai.
Sirf app ka late status update compensation ka proof nahi. Bank ke actual credit/reversal records, failure ki category aur delay ki dates matter karti hain. Na mile to bank se written calculation maangein. NPCI ke TAT instructions ko samajhne ke liye yeh do kalpanik examples dekhein:
Example 1: Dost Ko Rs 2,000 Bheje
1 October ko debit hua aur dost ko credit nahi ho saka. Applicable T+1 deadline 2 October hai. Agar reversal 3 October ko hua, to ek din ka delay hai; is eligible scenario me Rs 100 compensation banta hai. Original Rs 2,000 ka reversal isse alag hai.
Example 2: Dukaan Par Rs 850 Ka Payment
1 October ke merchant payment me debit hua, lekin merchant ko transaction confirmation nahi mili. Applicable T+5 deadline 6 October hai. Reversal 8 October ko ho to 7 aur 8 October, yani do din ka delay hai; eligible compensation Rs 200 hoga. Yeh successful purchase ke baad return/refund ka example nahi hai.
UPI Refund Ke Naam Par Scam Se Kaise Bache?
NPCI fraud awareness guidance ke mutabik paise receive karne ke liye QR scan karke UPI PIN enter karne ki zaroorat nahi hoti. Refund dilwane wala caller PIN maange to ruk jaayein.
- UPI PIN, OTP, card PIN aur banking password kisi ko na batayein.
- Refund receive karne ke naam par payment request approve ya test payment na karein.
- Unknown refund links na kholein; caller ke kehne par screen sharing/remote-access app install na karein.
- Customer care number official app ya bank website se lein; random search result ya social media reply par bharosa na karein.
phishing aur fake links ko pehchanna aise messages se bachne me madad karega. Banking/email logins ke liye strong password banana bhi useful hai; password aur UPI PIN alag credentials hain.
Payment aapne ki hi nahi? Ise normal failed transaction samajhkar refund ka wait na karein. Bank ke official fraud-reporting channel ko turant inform karein aur cybercrime authorities ko report karein. Google Pay ki fraud safety guidance bhi immediate bank reporting ki salah deti hai.
UPI Failed Payment Se Jude Aam Sawal
UPI failed hone par paise kab wapas aate hain?
Applicable personal-transfer failure me T+1 aur merchant-confirmation failure me T+5 ki deadline hai. Pehle actual debit, credit aur reversal status verify karein; har refund inhi cases me nahi aata.
UPI payment pending hai to kya karein?
Status, statement aur reference check karein. Final status verify kiye bina same payment repeat na karein; issue bana rahe to app/bank se contact karein.
24 hours baad bhi UPI refund nahi aaya to?
Bank complaint register karein aur transaction type batayein. T calendar date hai, exact 24-hour timer nahi. Deadline cross hui ho to reversal aur compensation dono ka written status maangein.
Merchant QR payment fail hua to kitna wait karein?
Debit aur merchant-confirmation failure wala case ho to T+5 applicable hai. Complaint pehle de sakte hain. QR personal account ka ho to bank se classification confirm karayein.
Google Pay ya PhonePe me complaint kaise karein?
Payment history me relevant transaction kholein aur uske support option se issue raise karein. Ticket save karein. App option na mile to debit wale bank se sampark karein.
UPI complaint number kaise track karein?
App ticket app support me, bank complaint bank ke official channel par, aur NPCI CRN uske complaint-status option se track karein. Transaction reference aur complaint number alag records hain.
Kya har delay par Rs 100 compensation milega?
Nahi. Covered failed transaction ki prescribed deadline aur actual credit/reversal delay matter karte hain. Wrong-recipient successful transfer ya ordinary merchant refund par ise automatic guarantee na samjhein.
Bank complaint resolve nahi karta to kahan jaayein?
Bank grievance process aur applicable NPCI route use karein. RBI escalation me 2026 eligibility aur 90-day filing limit dekhein; acknowledgement aur replies sambhalein.
UPI Payment Fail Ho Jaye To Ye Baatein Yaad Rakhein
Pehle status aur statement milayein, phir reference ke saath complaint karein. Pending payment ko bina verify kiye repeat na karein. Applicable deadline beetne par written follow-up karein aur refund receive karne ke liye kabhi PIN ya OTP share na karein.